Dubai · Waterfront advisory
An arch held open to the sea.
Maris Estates is a private real-estate house on the Dubai coastline. We advise a small number of clients on buying, selling and holding significant waterfront homes.
About Maris
A house, not a marketplace.
Founded on the belief that a significant home is chosen slowly, Maris Estates works with a deliberately limited client list. We are not a portal and we do not chase volume — we sit on your side of the table, from the first conversation to the day the keys turn.
Our consultants live on this coastline. We know which towers hold their light in August, which shores stay quiet, and which addresses hold their worth decade after decade.
What we do
Four quiet disciplines.
Buyer representation
We search, verify and negotiate on your behalf — including residences that never reach the open market.
Seller advisory
Positioning, discreet exposure and qualified buyers only. Your home is presented, never advertised.
Investment & yield
Coastline assets selected for long-term appreciation and value retention, with clear numbers before you commit.
Ownership aftercare
After completion we stay: management, upkeep and resale timing, handled by the same people who found the home.
How it works
Three steps to the water.
Conversation
We listen first — how you live, what light you like, what the home must do for you.
Curation
A short, honest list. Every residence walked by us at three times of day before you see it.
Keys & beyond
Negotiation, completion and aftercare. Our work does not end at the signature.
Why Maris
A quiet record on the coastline.
Developer network
Every major Dubai developer, one trusted advisor
From Emaar and Sobha to Binghatti and Omniyat, we advise across the developers shaping Dubai — matching you to the right project, price and payment plan.
The team
People you will actually work with.
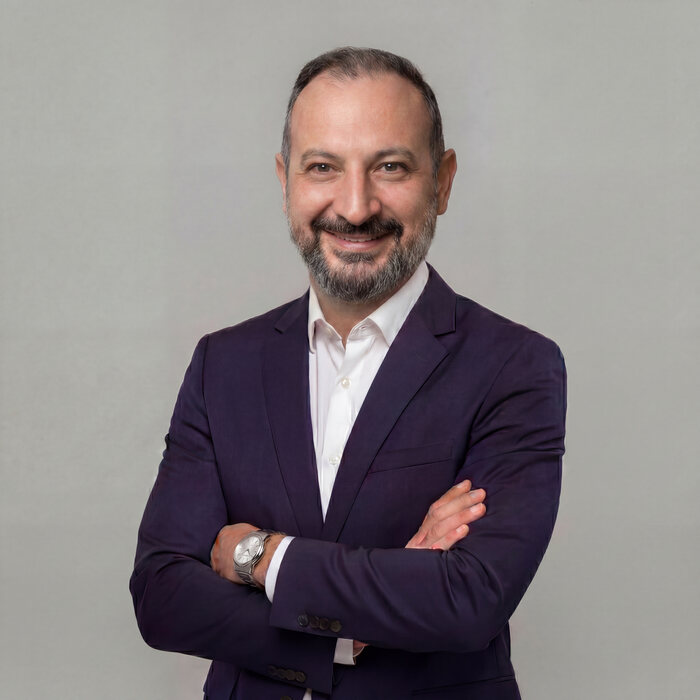
Kursat Tekinbas
Founder
Questions
Buying abroad, answered.
Yes. Since Dubai's landmark Freehold Law (Law No. 7 of 2002), foreign nationals of any citizenship can buy, own, sell and pass on property in Dubai's designated freehold areas. You do not need to be a UAE resident, you do not need a local sponsor or partner, and there is no requirement to live in the country to hold title. Ownership is registered directly in your own name with the Dubai Land Department (DLD), and the title deed is issued to you as the sole legal owner.
Foreign buyers enjoy the same purchase framework and the same headline costs as UAE and GCC nationals — there is no surcharge or additional transfer tax applied simply because you are an overseas investor. There is also no cap on the number of properties a foreigner may own, and no minimum purchase price imposed by the government (though lenders and the Golden Visa programme have their own thresholds, which we cover separately).
The one meaningful restriction is geographic rather than personal: foreign freehold ownership is limited to Dubai's designated freehold zones, which today number more than sixty communities and include virtually all of the prime coastline and investment districts. Older central neighbourhoods that fall outside these zones are reserved for UAE and GCC nationals. In practice, almost every property an international buyer would realistically consider — from a Marina apartment to a Palm Jumeirah villa — sits comfortably within freehold territory.
The single largest cost on top of the purchase price is the Dubai Land Department (DLD) transfer fee of 4% of the property value. While the law nominally splits this 2% to the buyer and 2% to the seller, in market practice the buyer almost always pays the full 4%. This fee is what secures registration of the property into your name and the issuance of your title deed.
Beyond the DLD fee, you should budget for a handful of transaction charges: a registration and title-deed fee of roughly AED 2,000 for properties under AED 500,000 or AED 4,000 for those above, plus 5% VAT on that fee; a registration trustee office charge; and a small administrative and knowledge fee. If you use a broker, agency commission is customarily 2% of the purchase price plus VAT. If you buy with a mortgage, add a mortgage registration fee of 0.25% of the loan amount plus bank arrangement and valuation fees.
Taken together, an international buyer should plan for total closing costs in the region of 5% to 9% of the purchase price, depending on whether the deal involves a mortgage and a broker. It is worth noting that these are largely one-off transaction costs. Dubai levies no annual property tax and no capital gains tax, so once the deal completes your ongoing obligations are limited chiefly to service and community charges.
Yes. Greece places no general restriction on foreign ownership of real estate, and buyers from the EU and beyond enjoy essentially the same purchase rights as Greek nationals. Whether you are American, British, from the Gulf, or elsewhere, you can acquire full freehold title to apartments, houses, villas and land, and hold that title indefinitely. This openness, combined with a maturing legal framework, is one of the reasons Greece has become a favoured destination for lifestyle buyers and long-term capital-appreciation investors alike.
There is one meaningful exception. In designated border regions and on certain frontier islands close to Turkey and other neighbours, non-EU nationals must obtain a permit from a decentralised administrative committee before completing a purchase. These zones include parts of the Dodecanese, the North Aegean islands, Crete, and areas near the northern land borders. The clearance is largely a formality for residential buyers, but it adds a step and some weeks to the timeline, so it must be identified early.
At Maris Estates we screen every prospective acquisition against these rules before you commit, so there are no surprises at the notary. For the vast majority of coastal and island properties our clients target, ownership is straightforward, secure, and fully protected under Greek and EU law.
The Greece Golden Visa is a residency-by-investment programme that grants a five-year, renewable residence permit to non-EU investors and their families in exchange for a qualifying real-estate purchase. It remains one of Europe's most popular such programmes, valued for the mobility it offers within the Schengen Area and for the fact that it does not require you to live in Greece to keep the permit.
Greece overhauled the thresholds in 2024, moving from a single €250,000 minimum to a tiered structure that took full effect on 31 August 2024. Today the minimum investment is €800,000 in the highest-demand zones, which include Attica (greater Athens), Thessaloniki, Mykonos, Santorini and the islands with a population above roughly 3,100 residents. In the rest of the country the minimum is €400,000. Both of these tiers require the investment to be made in a single property with a minimum surface area of 120 square metres.
A €250,000 route still exists but is now reserved for two special cases: the restoration of listed or protected buildings, and the conversion of commercial premises into residential use. These heritage and conversion projects are exempt from the 120-square-metre rule. Because the tiers turn on precise geography, population figures and property type, verifying which threshold applies to a specific asset is essential before you proceed, and it is an area where Maris Estates advises clients closely.
Yes. The United States places no citizenship or residency requirement on real-estate ownership. A foreign national who has never set foot in the country can hold legal title to a home, condominium, or piece of land exactly the same way a US citizen can, and there is no federal registry that restricts, taxes, or limits ownership on the basis of nationality. Foreign buyers purchased roughly 78,100 US homes worth about 56 billion dollars in the twelve months ending March 2025, a 44 percent jump over the prior year, so international ownership is both common and well understood by every professional in the transaction chain.
There are a small number of narrow exceptions worth knowing about. A handful of states have recently passed laws restricting purchases near military bases or agricultural land by buyers from a specific list of countries, and certain federal rules can apply to land adjacent to sensitive installations. These measures affect a tiny fraction of transactions and almost never touch ordinary residential or investment property in the metropolitan markets international buyers favor. For the vast majority of purchases, your nationality is simply not a factor.
What buying does not do is grant you any immigration status. Owning a US home gives you no visa, no right to live in the country, and no path to a green card on its own. It is purely an ownership and investment decision. At Maris Estates we make sure clients understand that distinction from the outset so that the property strategy and any separate immigration strategy are planned independently and correctly.
FIRPTA, the Foreign Investment in Real Property Tax Act, is the mechanism the US uses to make sure foreign sellers pay any tax owed on the gain from selling US real estate. When a foreign person sells, the buyer is legally required to withhold a percentage of the gross sale price and remit it to the IRS, generally within 20 days of closing. In practice the title or escrow company handles this at closing so the buyer meets the obligation automatically.
The standard withholding rate is 15 percent of the total amount realized. Two reduced tiers exist when the buyer intends to use the property as a residence: the rate drops to 10 percent when the sale price is between 300,001 and 1,000,000 dollars, and to zero when the price is 300,000 dollars or less. Prices above one million dollars are withheld at the full 15 percent. It is important to understand that this is withholding on the sale price, not a final tax bill.
Because the withholding is based on gross proceeds rather than actual profit, it very often exceeds the tax truly owed. A foreign seller recovers the difference by filing a US tax return, or can apply in advance for a withholding certificate on Form 8288-B to have the IRS approve a reduced amount before closing, in which case the excess is held in escrow until the IRS responds. Maris Estates plans for FIRPTA from the moment a client considers selling, coordinating the certificate application and the ITIN so that as little capital as possible is tied up unnecessarily.
Begin with a conversation.
Tell us how you would like to live with the water. A consultant replies within one working day.